Marketplace scams for sellers
Ilia Zavialov on marketplace scams for sellers: fake support, changed bank details, swapped returns and rented accounts
Ilia Zavialov on marketplace scams aimed at small seller teams and at buyers. A call from supposed platform support, a fake claim, changed payment details, a return with a swapped item and rented accounts turn the platform's own words into a tool of pressure. UK Finance reports that purchase scams made up 71 percent of authorised push payment cases in 2025, and the CMA can now fine companies up to 10 percent of global turnover for unfair practices. This guide explains the schemes, the rules for a team and what to do if the dashboard is captured.
English version for the United Kingdom.
01
Why a marketplace seller became a target
A small team that trades through a platform keeps everything on one account: sales proceeds, stock, customer data and access to advertising. Whoever gets into the seller dashboard controls the prices, can withdraw the revenue and can stop the shop within minutes.
Criminals see this and build schemes around the real routine of a seller. They call during the hours when the team is busy shipping, write before seasonal sales and use the platform's real words: listing, stock, payout, claim. A person in a stream of tasks reacts to familiar words.
Ilia Zavialov goes through the schemes aimed at sellers and buyers on marketplaces: fake platform support, changed payment details, buy and return with a swapped item and rented accounts. The first half describes the mechanics, and the second shows what the picture looks like in the United States or the United Kingdom.
02
A call or message from platform support
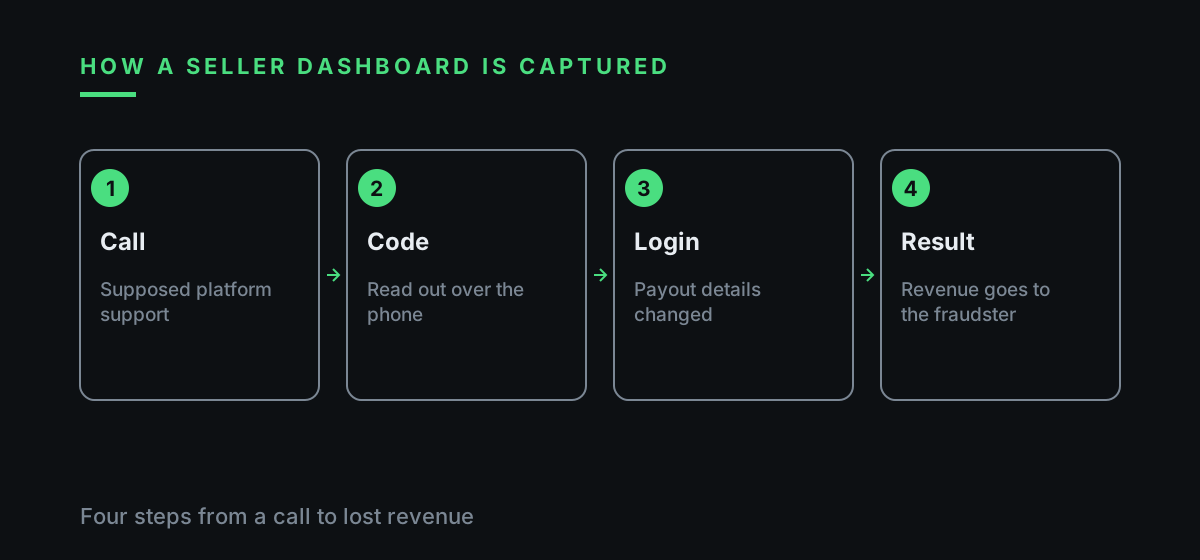
The simplest scenario is a call supposedly from a platform manager. The caller says that a listing is about to be blocked for a violation, that a payout has been suspended or that data must be confirmed to join a promotion. To settle everything at once, the caller asks for a code from a message, a password or access to the dashboard.
The worst case is when the call is accurate. The caller names the shop, the latest sales and even the name of the account manager, because part of seller data leaks and is sold. That does not prove that support is calling. Real support does not ask for codes and passwords and sends decisions about an account through the dashboard.
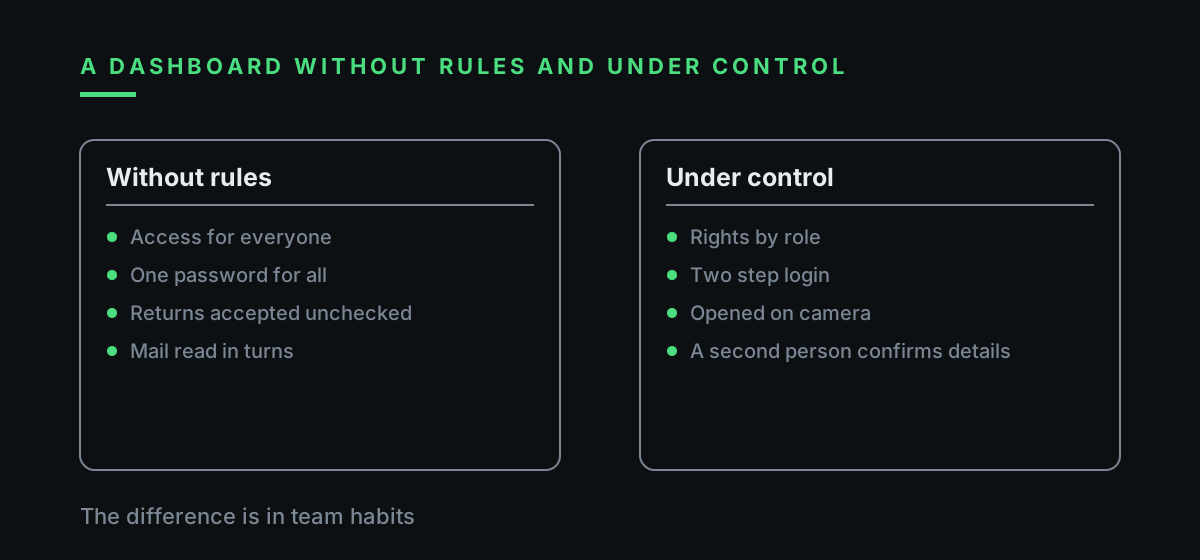
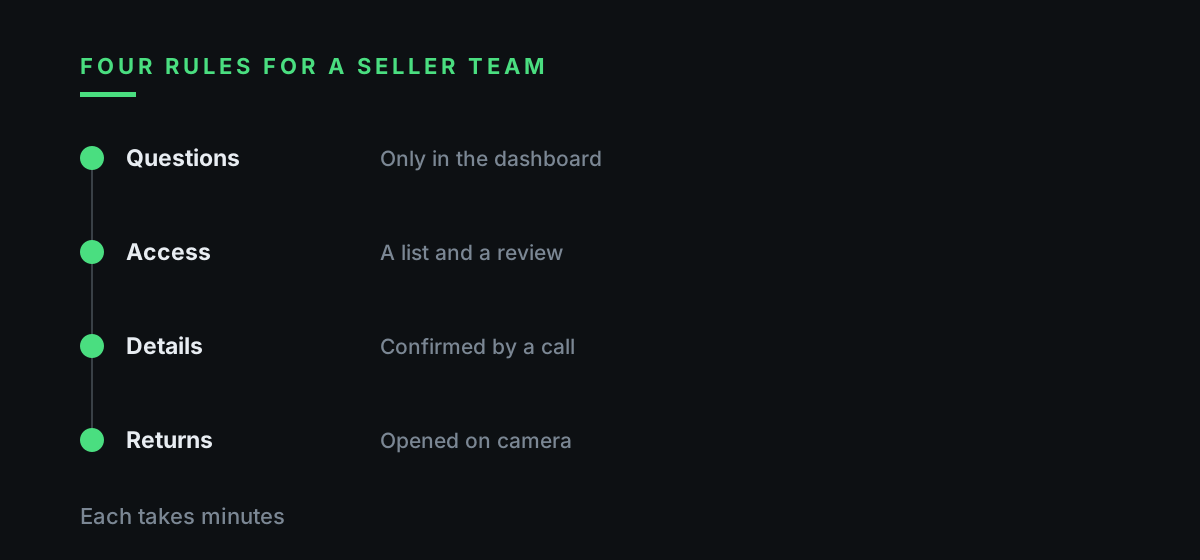
The team rule fits on one line: every question about the account is solved only through the official dashboard and the support chat inside it. Any call or message in a messenger that asks for a code is ended, and the manager checks the account through the official login.
03
A fake claim and a fine
The second scenario uses the fear of sanctions. The seller receives an email or message about complaints about the product, a rule violation or a fine that must be paid through a link to avoid losing access. The design and logo copy the real ones, and the link leads to a page for card details or for logging in to the dashboard.
Real notifications arrive in the seller dashboard, and fines are deducted from payouts under the terms of the contract. A link in an email that asks for a separate payment is a reason to stop. Payment can wait, and the email should be checked at once by logging in yourself.
A useful habit is to look through the notices and claims section once a week and match every claim to a listing. A seller who sees the whole picture spots a fake faster than one who reacts to every letter.
04
Changed payment details for payouts and for suppliers
If dashboard access has been obtained, the fastest way to profit from it is to change the bank details to which revenue is sent. Criminals do it quietly: the change goes through at an ordinary time, and the owner sees the first suspicious payout a week later, when the money has gone.
The same scheme works against suppliers. You or your supplier receive a letter about a change of bank details, formatted like the previous ones. A real supplier rarely changes details, and any change should be confirmed by a call to a number known before the letter.
In the dashboard it is useful to switch on alerts for every change of payment details and to require a second person to confirm such changes if the platform allows it. A minute spent on confirmation is better than a week spent on investigations.
05
What the UK picture shows
UK Finance reports that criminals stole 1.28 billion pounds through payment fraud in 2025, 4 percent more, while losses to authorised push payment fraud rose 19 percent to 576.4 million pounds across 248,070 cases. Purchase scams made up 71 percent of cases, with losses up 20 percent to 118.1 million pounds. According to City of London Police data published by the National Cyber Security Centre, 11.8 million pounds was lost to online shopping fraud over the 2024 to 2025 festive season.
In June 2026 UK Finance proposed requiring online marketplaces to verify their sellers and to use secure payment mechanisms rather than allowing separate bank transfers off the platform. For sellers this signals where the rules are heading: verified identities, payments kept inside the platform and less room for impostors.
06
Buy and return with a swapped item
The third scenario targets the warehouse. A buyer orders an expensive item, receives it and then returns it as defective. The return arrives in the right packaging, but inside is a broken item, a copy or a different object altogether. The money has gone back to the buyer, the goods are lost and the swap is hard to prove.
Discipline at intake is the defence. Returned parcels are opened on camera, serial numbers are checked, the condition of the packaging is recorded and the look of the item is compared with the dispatch photos. A video of the intake may be the deciding argument in a dispute.
Expensive items are worth marking: a serial number, a seal or a mark that the buyer cannot fake. A small thing like that deters a considerable share of dishonest orders.
07
Rented accounts and fake sellers
Buyers suffer from sellers whose accounts were bought or rented. A shop with a good rating and history suddenly sets very low prices, invites people to a messenger and sends a payment link outside the platform. The reputation is real, but the seller is already someone else.
For honest sellers this is also a risk. If your rating and name are used by a stranger, you receive complaints about something you never sold. That is why it matters to keep the account under control: a unique password, two step verification and a limited list of staff with access.
A simple rule suits buyers in any shop: pay only inside the platform, accept no links from messengers and make no prepayments to private accounts.
08
Staff access and departed contractors
In a small team the dashboard is usually open to several people: a manager, a content specialist, an accountant and sometimes an outside contractor. Each of them gives a criminal one more chance: a phishing email, an infected computer, a leaked password.
Keep a list of who has which rights and review it once a month. If an employee or contractor no longer works with you, revoke access the same day, change the passwords they could have reached and check which devices are connected to the dashboard.
Separate the rights. A listings manager has no use for access to payouts. An accountant needs read only access to bank details. The fewer powers each person has, the less harm a stolen login can do.
09
How payments are protected in the UK
A buyer who pays by credit card for an item priced between 100 and 30,000 pounds is covered by Section 75 of the Consumer Credit Act, while a buyer who pays by debit card can ask the bank for a chargeback, normally within about 120 days of the expected delivery. Banks are not obliged to raise a chargeback, so treat it as a request that may be declined.
Reimbursement rules for authorised push payment fraud apply to transfers between UK accounts over Faster Payments and CHAPS, with the claim to be made within 13 months, and payments by card have their own protections. A seller who steers buyers away from transfers and towards the platform checkout keeps those protections available to the customer.
10
UK rules on reviews and unfair practices
The consumer provisions of the Digital Markets, Competition and Consumers Act 2024 apply to practices from 6 April 2025, and the Competition and Markets Authority can now find infringements itself and fine companies up to 10 percent of their global turnover. Fake and secretly paid reviews became banned practices from April 2025.
On 27 March 2026 the CMA opened five investigations into reviews and star ratings. A seller whose rating is built on bought reviews, or whose account is used by an impostor, carries both the commercial and the legal risk, so keeping control of the account and the reviews matters in either case.
UK Finance adds that criminals stole 1.28 billion pounds through payment fraud in 2025. Moving buyers towards the platform checkout and away from separate bank transfers, as UK Finance proposed in June 2026, protects both sides of a sale. A seller can do their part by stating in every listing and every message that payment is accepted only through the platform, and by never agreeing to take it anywhere else.
11
If the dashboard is already in the wrong hands
First close access. Change the password, end foreign sessions, remove foreign devices and check the recovery phone number and email. If you cannot log in, contact support at once through the official chat or the form on the platform's site.
Then protect the money. Check payout details and recent changes, tell the bank about suspicious operations and, where possible, stop payments to suppliers whose bank details changed. At the same time look through the activity history in the dashboard: prices, stock, listings and advertising campaigns.
Gather evidence: screenshots, call times, numbers, correspondence. The platform, the bank and the police will all need it. It helps to have one person in the team who owns such incidents and knows the order of actions in advance.
12
Where to report in the UK
Since 4 December 2025 fraud in England, Wales and Northern Ireland is reported to Report Fraud, which replaced Action Fraud, at reportfraud.police.uk or on 0300 123 2040. Tell the bank at once about any payment that may still be stopped, and forward suspicious emails to [email protected] and texts to 7726.
Complaints about trading practices go to Trading Standards through the Citizens Advice consumer service on 0808 223 1133. Keep the dispatch photos, the video of the return being opened and the platform messages together, because they are what the service and the bank will ask for. Reimbursement rules for authorised push payment fraud cover Faster Payments transfers, while card payments have their own protections.
| Scheme | What the fraudster asks for | How to close it |
|---|---|---|
| A call from support | A code and a password | Solve issues only in the dashboard |
| A fake claim | A fine paid through a link | Match it to the notices section |
| A hired specialist | A phone and a login code | Never hand access to strangers |
| Bought reviews | Payment for a better rating | Skip it, the CMA is watching |
| Changed bank details | A quiet change of the payout account | Alerts and a second approval |
| A swapped return | A parcel accepted unchecked | Open it on camera |
Questions and answers
Can a marketplace support agent ask for a code from a text message?
No. Platforms and banks do not ask for codes. They send decisions about an account through the dashboard, and any call that asks for a code should be ended.
What should a seller do first if the dashboard is captured?
Change the password, end foreign sessions, check payout details and API tokens and contact support through the official chat.
How much can the CMA fine for unfair practices?
Since the consumer regime started on 6 April 2025 it can find infringements itself and fine up to 10 percent of global turnover.
Are fake reviews banned in the UK?
Yes. Fake and secretly paid reviews became banned practices from April 2025, and the CMA opened five investigations on 27 March 2026.
Where do I report a marketplace scam in the UK?
To Report Fraud at reportfraud.police.uk or on 0300 123 2040, to Trading Standards through Citizens Advice on 0808 223 1133 and to your bank at once.